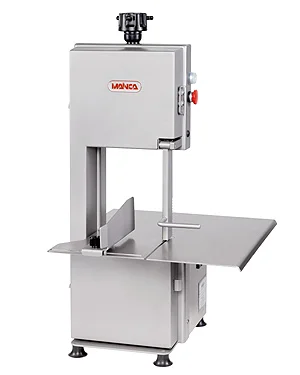
Compare the scope before comparing the price.
A compact table saw, an enclosed thickness saw and a scanning-based portioning line do different jobs. The pillar keeps dated market examples; this page helps compare complete offers and your own cost assumptions without inventing an industry-average price.
Ask each bidder to mark included, optional or excluded
| Quote line | Request in writing | Comparison boundary |
|---|---|---|
| Machine and feeding | Exact model/version, table/carriage, holders/grippers, infeed and outfeed. | Do not compare a bare cutting head with a complete loaded system. |
| Portion control | Thickness setting, scanning/weight function, recipe capability and downstream checking. | A uniform distance setting is not automatically target-weight control. |
| Blade and spares | Approved blade item, initial quantity, replacement supply and proposed consumables. | Use itemised prices and quantities; do not assume universal blade life. |
| Site and delivery | Destination configuration, drawings, electrical/utility requirements, shipping and unloading scope. | Confirm what is included rather than inferring it from a headline price. |
| Support and handover | Installation/training scope, service route, documents and responsibility for the product trial. | Do not invent warranty terms, response times or legal obligations. |
Explore your cost per accepted kilogram
Use one currency throughout. The prefilled values are an illustrative scenario only, not a quote, expected blade life or measured production rate. This straight-line planning calculation excludes financing, tax, resale value, ingredient cost, building cost and profitability.
See the formula and its limits
Annual planning cost = equipment cost ÷ planning years + operating hours × operators × labour cost + annual blades/consumables + annual service + operating hours × utilities cost per hour.
Annual accepted mass = operating hours × accepted kg per hour. Cost per accepted kg = annual planning cost ÷ annual accepted mass.
The example produces 25,000.00 currency units per year, 100,000.00 accepted kg per year and 0.2500 currency units per accepted kg. Planning years are your accounting assumption, not a manufacturer service-life claim. Avoid counting the same cleaning or downtime loss both in hours and output rate.
Compare sensitivity rather than claiming a guaranteed saving
Change accepted output, staffing and annual hours one at a time. Use demonstrated output and your own labour/utility costs when available. A higher purchase price can only be evaluated against the complete duty and your actual assumptions; this tool does not calculate a guaranteed payback or recommend an investment.
General equipment trial and quotation guide · Dated public market examples
Continue the decision
Bone Saw Trial Record: Yield, Portion Weight & LossesBone saw types, working principles and dated market pricesSources and scope
Reviewed 2026-11-04. Manufacturer statements support the particular product or catalogue scope. Buyer questions, worksheets and arithmetic are editorial planning aids; they are not tested machine results or operating instructions. Manufacturer images remain attributed equipment references.
Source URLs, plain text
- https://kolbe-foodtec.com/en/product/bandsaws/k430-en/k430-2/
- https://www.astech.es/en/machines/sra-compact/
- https://www.astech.es/en/machines/pw-saw/